What Is a Bank Statement Loan? (And How It Helped One Client Buy a Home)
If your income doesn't look the way a bank expects it to, because you're self-employed, work gig or contract jobs, or your tax write-offs make your "official" income look smaller than what you actually bring home, a conventional mortgage can be surprisingly hard to qualify for. That's where a bank statement loan comes in.
Instead of qualifying you based on tax returns and W-2s like a conventional loan does, a bank statement loan looks at 12 to 24 months of your actual bank deposits to verify income. It's built specifically for people whose real cash flow doesn't match what shows up on paper. The trade-off is that these loans typically come with slightly higher rates and down payment requirements than conventional financing, but for someone with unconventional income, they're often the only path to qualifying at all.
Here's what that looked like in real life.
The Client Who Literally Ran to Find Me
C literally ran up to me at an open house, one I wasn't even hosting, to introduce herself. That's how this story starts, and honestly, it's a pretty good preview of the energy C brought to the entire home search.
Starting From "Impossible"
C had been a homeowner once before, years ago, prior to her divorce. But over a decade later, on a single income, as a single woman navigating a brutal market, homeownership had started to feel like something that happened to otherpeople. C was discouraged before we ever sat down together.
So that's where we started. Not with listings, but with realistic expectations. We talked through budget, through timeline, through what C actually needed versus what she thought she was supposed to want. Some of that conversation touched old wounds. There were tears. There was also, eventually, a plan.
The Search Nobody Warns You About
If you think house hunting is just scrolling photos and touring pretty kitchens, this journey will cure you of that idea.
We tried for a couple of fixer-uppers first. Then a short sale that quietly morphed into a foreclosure auction, which, if you've never dealt with one, is its own special kind of chaos. None of it worked out. All of it taught us more about what C actually wanted.
The One
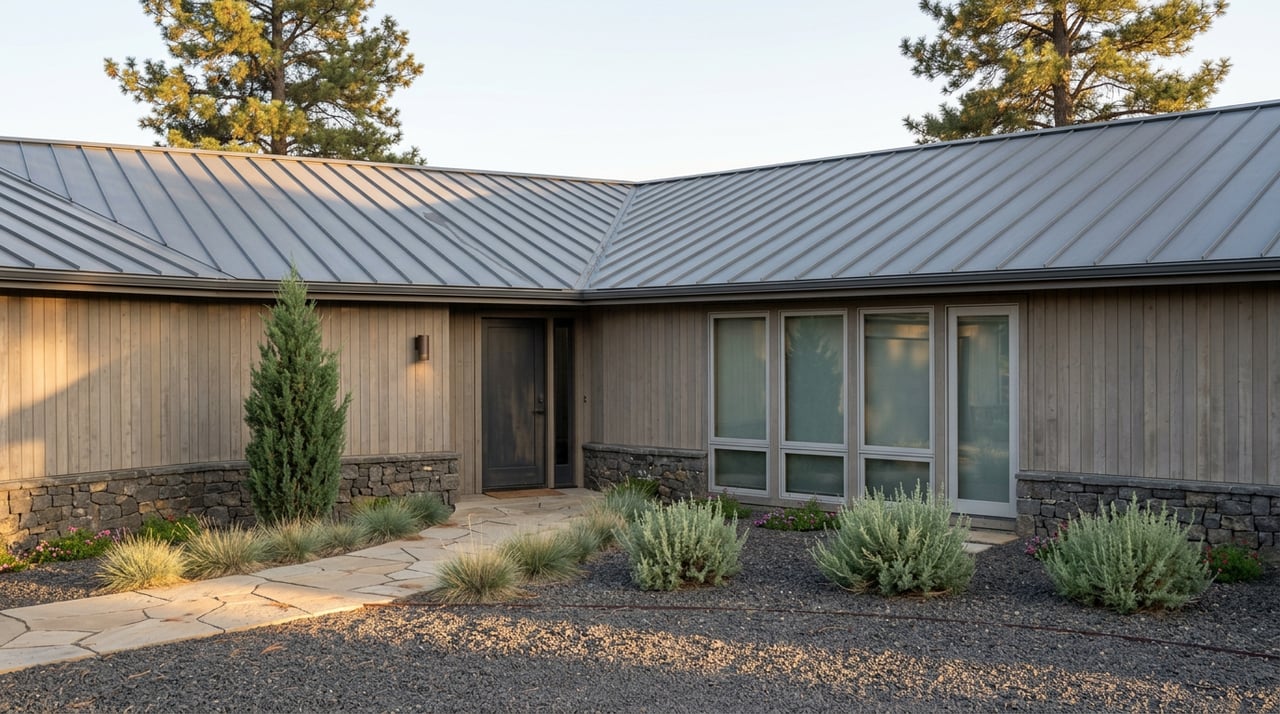
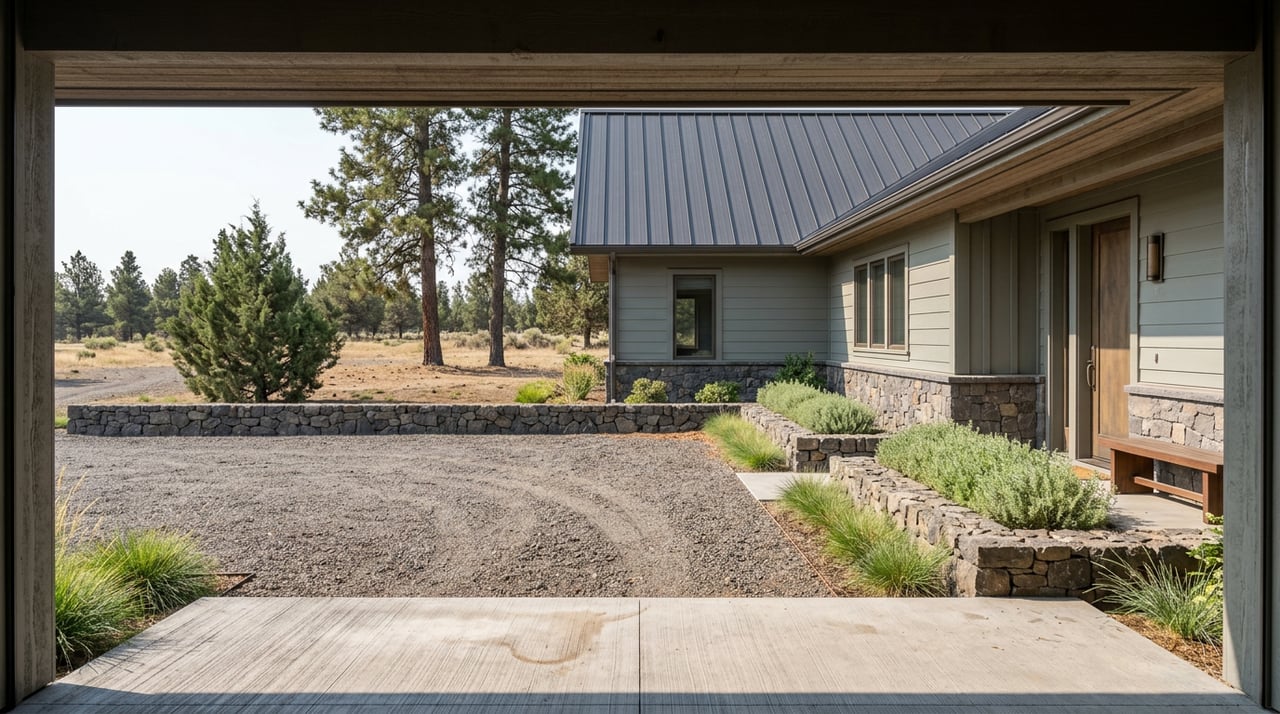
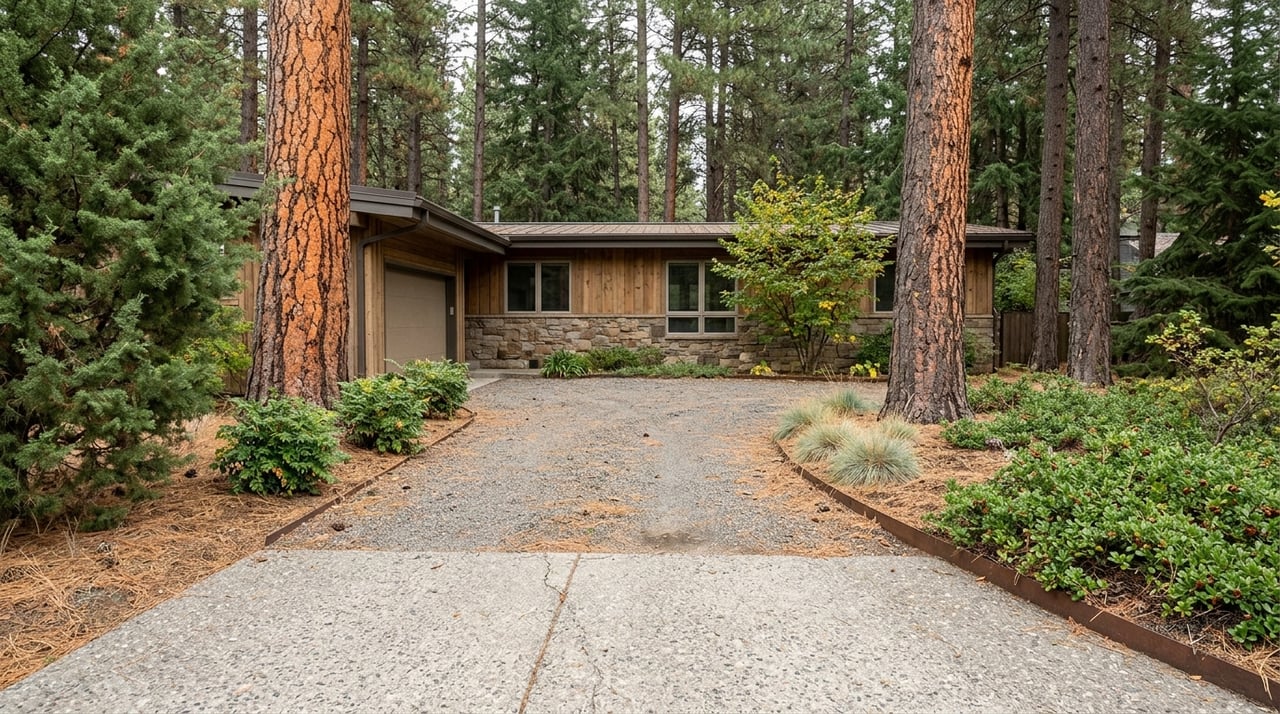
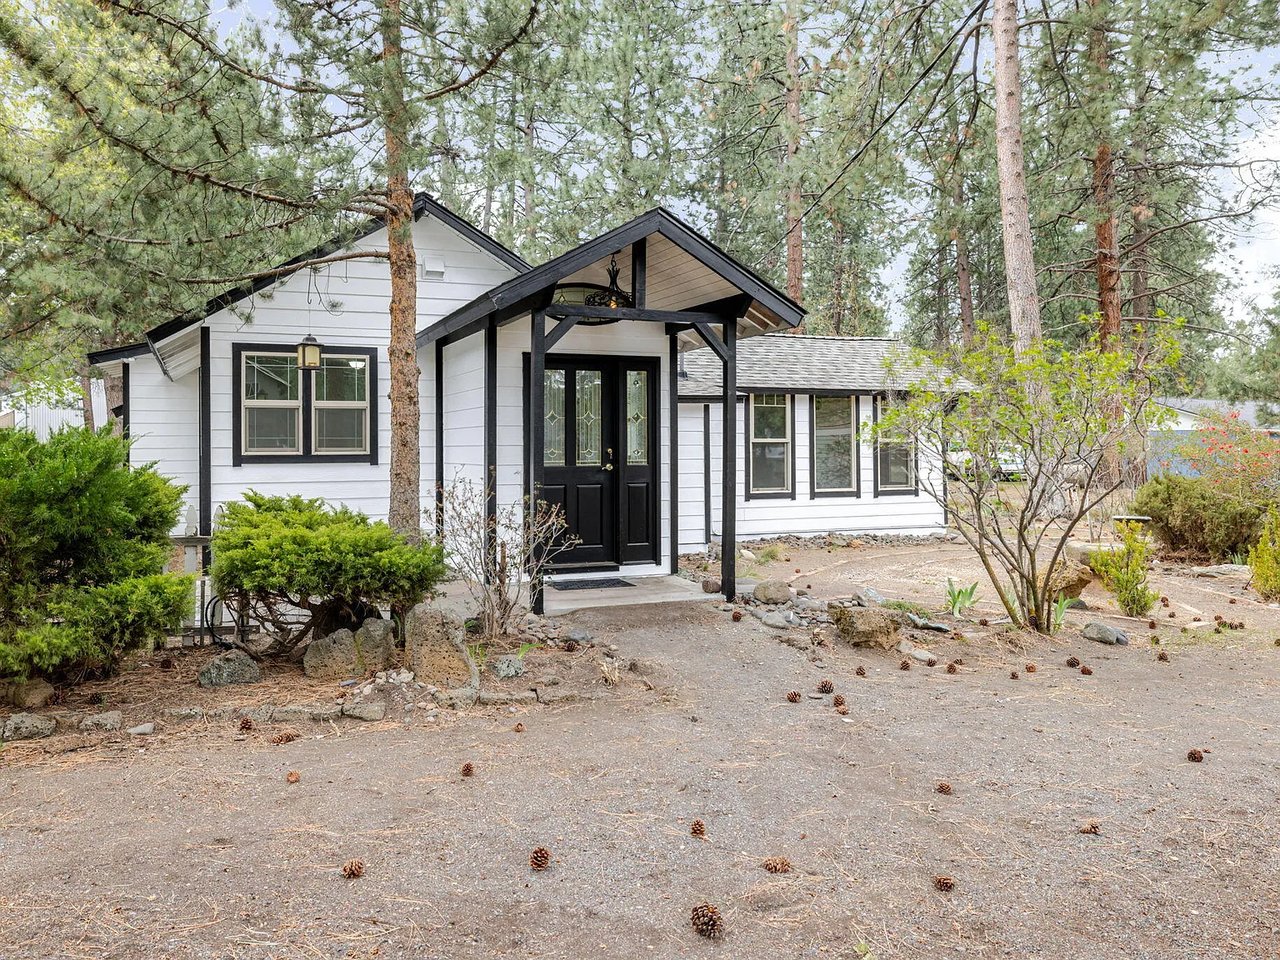
Eventually we found it: a single-level home on nearly an acre, ten minutes from downtown, under $500k. It was getting a brand new septic system installed, which meant our offer came with a contingency subject to the septic final being issued. Not exactly standard fare, but it protected C.
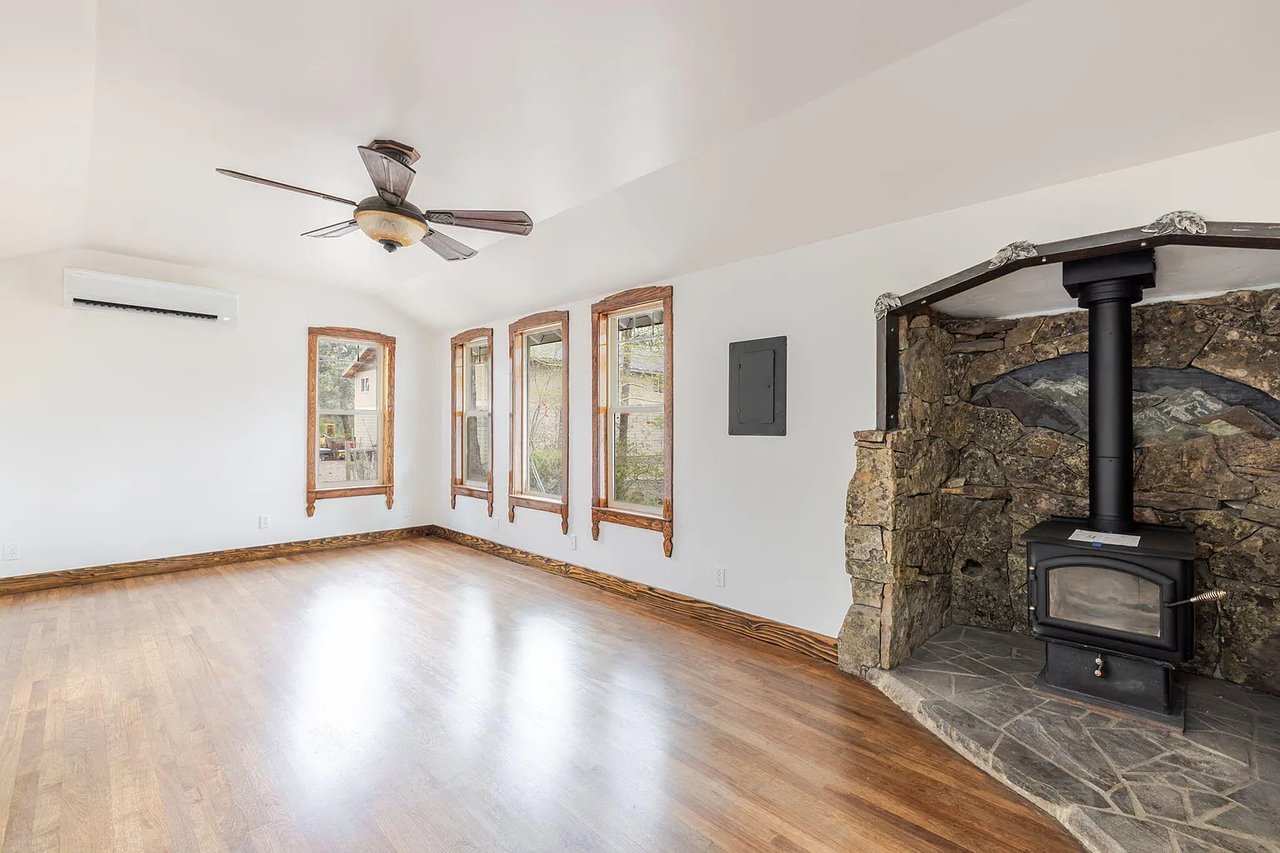
And the fireplace? Built from stacked rock that, if you look closely, actually forms the silhouette of the Cascade mountain range.
Where the Bank Statement Loan Came In
This is where C's own income situation ran headfirst into the problem described above. C earns her living doing in-home care nursing, real, steady income, but the kind that gets muddied by write-offs and deductions once it hits a tax return. On paper, her taxable income looked a lot smaller than what she actually brings home, and a conventional loan wasn't going to work.
A bank statement loan was the answer. C's actual deposits told the true story of her income, and that's what got her qualified, turning "this feels impossible" back into "this might actually happen."
Getting to Yes
With financing sorted, we wrote an offer and landed her a home at $475,000.
Why This One Stays With Me
This wasn't a fast transaction or an easy one. It was fixers that fell through, a foreclosure curveball, a nontraditional loan, and a client who kept showing up anyway.